Bitcoin Slides Near $68,408 as $1.47 Billion in Crypto Liquidations Meet Fed and Nvidia Shock
Leveraged long positions dominated a roughly $1.47 billion liquidation wave as bitcoin tested sub-$70,000 levels alongside macro tension and turmoil in AI-linked equities.
6 min read
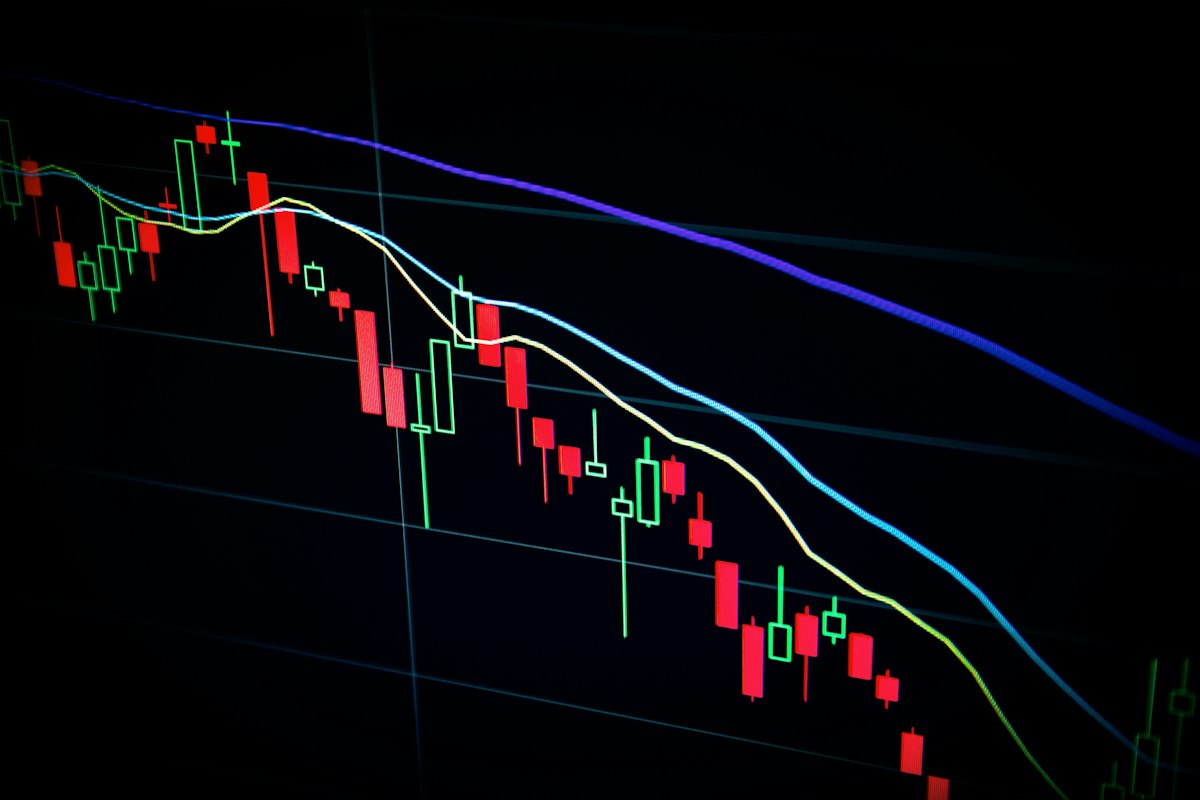
Bitcoin spent November 12, 2026, trapped between macro anxiety and a sudden repricing of AI-linked risk, sliding toward sixty-eight thousand four hundred eight dollars on major venues while derivatives exchanges forced more than one point four seven billion dollars in liquidations across the digital asset complex. The session extended a drawdown that had already erased hundreds of billions in token market capitalization since October, and it overlapped almost precisely with Nvidia’s intraday crash after Jensen Huang resigned as chief executive. Correlation traders argued about causation, but the timeline left little doubt that cross-asset portfolios were unwinding together.
Price action and support levels
Spot data from Bitstamp and other large exchanges showed bitcoin touching intraday lows near sixty-seven thousand five hundred dollars in early U.S. hours before stabilizing close to sixty-eight thousand. Ethereum fell through two thousand dollars on several pairs, and Solana led a broader altcoin decline that punished tokens with the highest open interest. Technical analysts highlighted the loss of bitcoin’s two-hundred-day moving average as a signal that momentum funds might remain defensive into year-end.
The dollar index held near nineteen-month highs, adding pressure to assets priced in U.S. dollars. Some desks cited geopolitical headlines, including renewed tension in the Middle East, as a secondary catalyst that reduced appetite for speculative beta. None of that fully explained the speed of the move; leverage was the accelerant.
Liquidations by the numbers
Coinglass and independent aggregators published snapshots that differed by measurement window but agreed on direction: long positions dominated forced closures. On a twenty-four-hour rolling basis, total crypto liquidations approached or exceeded one point four seven billion dollars, with bullish bets accounting for roughly ninety percent of the total. Bitcoin alone represented several hundred million dollars of that figure on some dashboards, while a narrower UTC calendar-day panel showed nearly three hundred million dollars across all coins.
The concentration of long liquidations implied that traders had positioned for a year-end rally or at least a shallow dip-buying environment. When spot broke support, exchanges issued margin calls in waves. A reported thirty-one-million-dollar long liquidation on Hyperliquid became the session’s symbolic trade—the largest single print on a decentralized venue, underscoring how on-chain leverage had scaled alongside centralized futures books.
Fed policy and macro calendar
Federal Reserve officials had spent the prior week pushing back against market bets on rapid easing. Vice Chair comments and regional president speeches reinforced a higher-for-longer narrative even as growth data softened. For bitcoin, which had traded as both an inflation hedge and a liquidity sponge, that messaging removed one pillar of the bull case without immediately offering a recession hedge narrative strong enough to attract fresh macro buyers.
Traders now watch the next consumer and labor prints for evidence that the Fed must pivot. Until then, funding rates on perpetual swaps have normalized from overheated levels, but remain positive—suggesting carry traders still prefer long exposure if volatility subsides. Options skew tilts toward puts on major strikes near sixty-five thousand dollars, a level that coincides with on-chain cost-basis estimates cited by several research shops.
The Nvidia catalyst and correlation trade
Nvidia’s open-down move on Huang’s resignation transmitted shock through every basket labeled “AI” or “semiconductor liquidity.” Crypto funds with hybrid equity-crypto books reportedly sold bitcoin to rebalance risk limits even when their thesis on on-chain adoption was unchanged. Public miners with treasury strategies faced a double hit: equity beta from tech sells-offs and spot weakness in the asset on their balance sheets.
Correlation between bitcoin daily returns and Nasdaq mega-cap indices had already risen in 2026 as passive strategies lumped “growth” exposures together. November 12 was the stress test. Some quantitative funds reduced leverage across the board rather than disentangle idiosyncratic drivers—a classic portfolio insurance response that amplifies single-headline days.
ETF flows and stablecoin signals
Spot bitcoin exchange-traded funds in the United States registered outflows in the days leading up to the liquidation flush, according to issuer reports aggregated by research firms. Five-day totals near one point four billion dollars in redemptions appeared in several commentaries, echoing similar figures from prior weeks. Outflows do not cause spot prices by themselves, but they remove a structural bid that had cushioned declines earlier in the year.
Stablecoin supply metrics, watched as a proxy for dry powder, showed modest contraction on some trackers—ambiguous signal. Rising supply usually precedes buying; shrinking supply can mean redemption into fiat or rotation into yield products. Neither reading was decisive on November 12, which suggests traders were reacting to price momentum more than preparing new deployment.
Who got hurt and who stepped in
Retail flow data from at least one U.S. brokerage platform showed dip-buying in Nvidia after the initial plunge; similar patterns appeared in bitcoin once prices stabilized near sixty-eight thousand. Professional liquidations, however, were dominated by funds using two-times to twenty-times leverage on perpetual contracts. Market makers widened spreads temporarily, increasing slippage for anyone attempting to hedge during the cascade.
DeFi lending protocols reported elevated utilization on collateral types tied to ether and bitcoin, but no systemic protocol failures as of the U.S. close. Risk officers at centralized exchanges emphasized automatic deleveraging mechanisms that prevented socialized losses, while reminding users that extreme gaps can still fill stops far from mid prices.
Scenarios for the next week
If macro data softens enough to revive Fed-cut pricing, bitcoin may attempt a reclaim of seventy thousand dollars, though overhead supply from trapped longs could cap rallies. A continued grind lower targets sixty-five thousand and, on some models, fifty-two thousand seven hundred—a level tied to long-term holder cost bands cited in on-chain studies.
Regulatory headlines remain a wild card. U.S. chip export politics intensified the same day, indirectly linking crypto markets to Capitol Hill debates that rarely mention bitcoin by name. Asia hours will test whether Korean and Japanese retail buyers repeat their August pattern of buying tech-linked drawdowns.
Takeaway for allocators
November 12 was not a single-factor crash. It was a leverage event intersecting dollar strength, ETF outflows, and an equity shock in the sector most correlated with crypto’s 2025–2026 narrative. Risk managers should treat one-point-four-seven-billion-dollar liquidation days as diagnostics: they reveal positioning, not destiny. Builders and long-horizon holders face a different question—whether on-chain adoption metrics decoupled from prices before the flush resumes, or whether another quarter of integration data is required to rebuild confidence.
Exchange and regional breakdown
Liquidation dashboards attributed heavy share to Binance and Bybit books, reflecting where open interest concentrated before the break. Korean venues saw amplified spot-volume narratives as retail platforms published buy-sell ratios favoring purchases. European hours added ether liquidations as carry traders unwound cross-margin positions that treated ether beta as a hedge for tech equities—a linkage that failed when both legs fell together.
Historical framing
Days with more than one billion dollars in crypto liquidations are no longer rare, but pairing them with a CEO exit at the world’s largest AI chip vendor is novel. Veterans compared November 12 to March 2020 and May 2021 flush events, noting that recovery timelines then depended on macro pivots more than crypto-native catalysts. This time, equity and crypto may need separate bullish triggers rather than a single liquidity injection narrative.
More in cryptocurrency
Cubed
Write about the technologies shaping the future.
For developers, founders, and curious minds exploring AI, crypto, Web3, and emerging tech—signal over noise.
One free account across In Plain English, Stackademic, Venture, and Cubed.
How it works- AI, crypto & Web3
- Software & emerging technologies
- Analysis & practical resources
- Thoughtful voices, not hype
Sign in
Google or GitHub
Complete profile
Takes a few minutes
Get approved & publish
Start sharing
Why write for Cubed?
The future deserves thoughtful voices, not just louder headlines.
Comments
Loading comments…